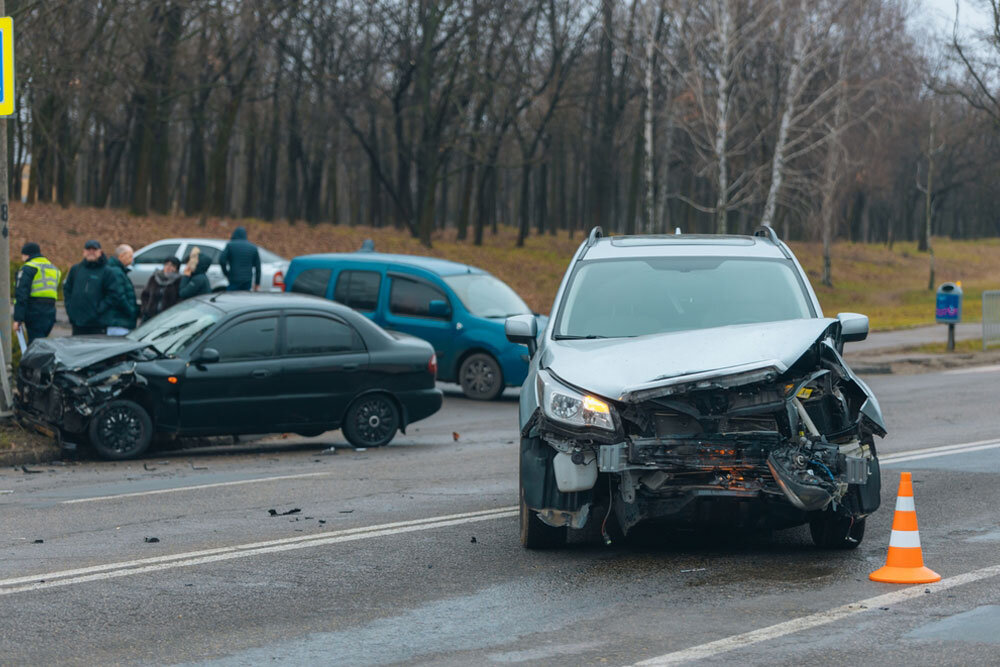
Uber and Lyft accidents can look like ordinary car crashes from the outside. Two vehicles collide, someone is injured, and an insurance claim follows. Behind the scenes, however, determining which insurance policy applies can be considerably more complicated.
The reason is that rideshare insurance changes according to what the driver was doing in the app at the exact moment of the collision.
A driver who has the Uber or Lyft app turned off is in a very different insurance position from a driver who is logged in and waiting for a passenger. Coverage changes again after the driver accepts a ride, and another important set of protections applies once the passenger enters the vehicle.
California divides transportation network company activity into three primary coverage periods. For an accident victim, determining the correct period can affect which insurer receives the claim, how much liability coverage may be available, whether uninsured or underinsured motorist coverage applies, and how the case should be investigated.
That is why one of the first questions after a rideshare collision should be: What was the Uber or Lyft driver's exact app status when the crash happened?
What Are the Three Uber and Lyft Insurance Periods?
California regulates companies such as Uber and Lyft as transportation network companies, commonly called TNCs. The state's insurance framework separates rideshare activity according to the driver's relationship with the app and passenger.
- Period 1: The driver is logged into the rideshare app and available to receive a request, but has not yet accepted a passenger.
- Period 2: The driver has accepted a ride and is traveling to pick up the passenger.
- Period 3: The passenger has entered the vehicle and the ride continues until the passenger exits.
There is also an important situation that comes before Period 1: the app is completely off. When the driver is not using the rideshare platform, the driver's ordinary personal automobile insurance generally becomes the primary insurance to examine.
These distinctions may sound technical, but they can have major consequences after a serious crash.
What Happens When the Uber or Lyft App Is Off?
If a rideshare driver is operating the vehicle for personal purposes and is not logged into Uber or Lyft, the accident generally begins like any other collision involving a private motorist.
The driver's personal automobile insurance is the primary policy to investigate.
For example, suppose an Uber driver finishes working, logs out of the application, and drives to a grocery store. If the driver causes a collision on that personal trip, Uber's rideshare liability coverage generally would not apply simply because the person happens to work as an Uber driver.
The critical issue is what the driver was doing at the moment of the crash, not whether the driver has an Uber or Lyft account.
This makes evidence about app status extremely important. A driver might tell someone at the scene that they were "working," but that description does not establish the specific rideshare period. Conversely, a driver may say they were not carrying a passenger even though they had already accepted a request and were traveling toward the pickup location.
The precise electronic data can matter more than casual statements made after the collision.
How Does Period 1 Coverage Work?
Period 1 begins when the rideshare driver logs into the platform and is available to accept a passenger request but has not yet accepted one.
Under current California requirements, TNC insurance during this period must provide at least:
- $50,000 for death or personal injury to one person;
- $100,000 for death or personal injury per incident; and
- $30,000 for property damage.
California also requires at least $200,000 in excess coverage per occurrence during this period for qualifying liability exceeding the primary Period 1 limits.
Period 1 is important because personal automobile policies frequently contain restrictions or exclusions involving commercial or rideshare activity. A driver should not assume that a standard personal policy will provide ordinary coverage once the rideshare application is active.
For someone injured by a rideshare driver during Period 1, identifying the driver's status can therefore reveal insurance protection that may not be obvious from the insurance card exchanged at the scene.
Why Can Period 1 Cause Insurance Disputes?
Period 1 sits between personal driving and an active passenger trip.
The driver is working through the platform in the sense that the app is active, but there is no accepted ride and no passenger yet. Historically, that transition created significant uncertainty between personal and commercial insurance, which is one reason California established specific TNC insurance requirements.
Imagine a Lyft driver is parked while waiting for a request. The driver begins moving toward a busier part of town while remaining logged into the Lyft platform and causes a collision before receiving a ride request.
There is no passenger. There is no accepted trip. But the driver is not simply using the vehicle privately either. That situation generally falls within Period 1.
If an injured person reports the collision only to the driver's personal insurer without investigating the rideshare activity, important coverage information may be missed.
What Is Period 2 in an Uber or Lyft Accident?
Period 2 begins when a rideshare driver accepts a passenger's request and continues while the driver travels to the passenger's pickup location.
This period is particularly important because the level of required liability coverage rises substantially.
Under current California law, once the driver accepts the ride request, transportation network company insurance must provide primary coverage of $1 million for death, personal injury, and property damage, subject to the policy and applicable law.
The passenger does not need to be physically inside the Uber or Lyft vehicle for this primary liability requirement to begin.
That point can be extremely important after a serious collision.
Suppose an Uber driver accepts a ride at the airport and causes an accident while traveling toward the passenger's pickup point. Even though the passenger has not yet entered the vehicle, the accepted request has moved the driver from Period 1 into Period 2.
That changes the insurance investigation substantially.
What Is Period 3?
Period 3 begins when the passenger enters the rideshare vehicle and continues until the passenger exits.
This is the period most people naturally associate with an Uber or Lyft trip. The driver has the passenger in the vehicle and is transporting that person toward the requested destination.
The $1 million primary TNC liability requirement continues during this period.
Period 3 is also especially important when a crash is caused by someone other than the rideshare driver because California requires the transportation network company to maintain uninsured and underinsured motorist protection for passengers during this portion of the ride.
Beginning in 2026, California requires that Period 3 UM/UIM protection provide $60,000 per person and $300,000 per incident.
That coverage may become relevant when an uninsured driver, hit-and-run driver, or inadequately insured driver causes the accident. The exact application of coverage depends on the facts, policy terms, damages, and other available insurance.
What If the Uber or Lyft Driver Caused the Crash?
If a rideshare driver caused an accident through negligence, the applicable insurance depends heavily on the driver's status.
If the app was off, the claim generally begins with the driver's personal auto insurance.
If the driver was logged in but had not accepted a ride, Period 1 coverage must be examined.
If the driver had accepted a request or was transporting the passenger, the $1 million primary TNC liability coverage applicable to the accepted-trip period becomes particularly important.
Examples of rideshare driver negligence may include:
- Running a red light or stop sign;
- Speeding;
- Unsafe lane changes;
- Following another vehicle too closely;
- Driving while distracted by the rideshare application;
- Making an unsafe pickup or drop-off maneuver;
- Driving while fatigued;
- Failing to yield;
- Driving under the influence; or
- Otherwise failing to operate the vehicle with reasonable care.
The presence of substantial insurance does not eliminate the need to prove negligence and damages. The insurer may still dispute how the accident occurred, whether the injuries were caused by the crash, how much medical treatment was necessary, and what the claim is worth.
What If Another Driver Caused the Rideshare Accident?
Not every Uber or Lyft accident is the rideshare driver's fault.
Suppose you are a passenger in an Uber when another motorist runs a red light and crashes into your rideshare vehicle. The primary liability claim would ordinarily focus on the negligent driver's insurance.
The problem becomes more complicated when that driver has no insurance or too little insurance to compensate for serious injuries.
If you were already inside the rideshare vehicle, Period 3 UM/UIM coverage may become relevant.
Underinsured motorist claims can become particularly important when injuries are substantial. A driver carrying only California's minimum personal liability coverage may not have enough insurance to compensate someone who suffers surgery, permanent impairment, extended wage loss, or another serious injury.
A lawyer handling the case should investigate all potentially applicable policies rather than assuming the at-fault motorist's insurance is the only possible recovery source.
What If I Am Hit by an Uber or Lyft Driver but I Am Not a Passenger?
Rideshare insurance does not protect only the passenger sitting inside the Uber or Lyft vehicle.
Other people injured by a negligent rideshare driver may have claims as well.
That can include:
- Drivers of other vehicles;
- Passengers in other vehicles;
- Pedestrians;
- Bicyclists;
- Motorcyclists; and
- Other people injured as a result of the collision.
For these accident victims, the rideshare driver's app status still matters.
A pedestrian struck while a Lyft driver is traveling to pick up a passenger may be dealing with Period 2 coverage. Another motorist struck while an Uber driver is merely online and waiting for a request may be dealing with Period 1.
The victim does not need to have personally ordered an Uber or Lyft ride for the driver's rideshare status to affect the insurance claim.
How Do You Prove Which Coverage Period Applied?
This question can become one of the most important parts of a rideshare accident investigation.
Evidence can potentially include the rideshare company's electronic records showing when the driver logged in, accepted the ride, reached the pickup location, began the trip, ended the trip, or logged off.
Other useful evidence may include:
- The passenger's Uber or Lyft trip receipt;
- App screenshots;
- Text messages between the driver and passenger;
- Pickup and drop-off information;
- GPS information;
- Driver statements;
- Passenger statements;
- Police reports;
- Phone records when legally obtainable;
- Electronic rideshare records; and
- Insurance documents identifying the applicable TNC policy.
A rideshare company possesses data that an accident victim may not have immediate access to. Preserving and obtaining that information can therefore become an important part of the legal process.
Why Should You Not Rely Only on the Driver's Insurance Card?
An insurance card exchanged after a collision may identify only the driver's personal automobile insurer.
That information can be useful, but it may tell only part of the story.
If the driver was actively using Uber or Lyft, separate TNC insurance may apply according to the driver's coverage period.
This creates a common problem after rideshare crashes. A victim contacts the personal insurer shown on the driver's card, and the insurer responds that the driver was engaged in rideshare activity and therefore coverage is excluded or limited under that policy.
An accident victim might interpret that response as meaning there is no insurance.
That conclusion could be wrong.
The next question should be whether Uber, Lyft, or another transportation network company's coverage was active at the time.
What If the Rideshare Driver Was Using More Than One App?
Some drivers work with both Uber and Lyft or use multiple gig-economy applications.
If more than one application was active when a collision occurred, identifying which company was responsible for providing coverage can become more complicated.
For example, a driver may have both Uber and Lyft online while waiting for a request. Once the driver accepts a trip through one platform, the driver's status with the other application may affect the insurance analysis.
These situations should be investigated using actual electronic platform records rather than assumptions.
The presence of multiple apps also makes it especially important for a lawyer to determine exactly when each platform was activated, whether a ride had been accepted, and which company's trip the driver was performing.
Are Uber and Lyft Automatically Responsible for Everything Their Drivers Do?
No. The existence of rideshare insurance does not mean Uber or Lyft automatically becomes legally responsible for every act of a driver.
Liability and insurance coverage are related but separate issues.
California's transportation network company system includes insurance requirements specifically designed to address accidents occurring while drivers use the platforms. Whether the rideshare company itself can be held independently liable under a particular legal theory is a separate question requiring analysis of the facts and applicable law.
The immediate insurance claim may therefore focus on coverage maintained for the participating driver without necessarily establishing separate direct negligence by the rideshare company itself.
A strong case distinguishes between who was negligent, who may be legally responsible, and which insurance policies can respond to the loss.
What Compensation Can Be Available After a Rideshare Accident?
A person injured through another party's negligence may potentially pursue compensation for legally recoverable damages resulting from the accident.
Depending on the case, those damages can include:
- Past medical expenses;
- Reasonably necessary future medical care;
- Lost earnings;
- Loss of future earning capacity;
- Pain and suffering;
- Physical limitations;
- Emotional consequences of the injury;
- Property damage; and
- Other qualifying losses supported by the evidence.
The amount of insurance available does not automatically determine the value of the injuries. A serious injury can be worth more than an applicable policy limit. Insurance coverage determines how much a particular insurer may be required to pay, while damages address the actual loss caused by the accident.
What Should You Do After an Uber or Lyft Accident?
If your physical condition allows it, document as much information as possible.
Take photographs of the vehicles, roadway, license plates, visible injuries, and surrounding area. Obtain the names and contact information of witnesses. If you were the rideshare passenger, preserve the trip information in the application rather than assuming it will always remain easily accessible.
Screenshot information showing the driver's name, vehicle, pickup location, destination, trip time, and ride status.
Seek appropriate medical attention for your injuries and explain accurately how the collision occurred and what symptoms you are experiencing.
Also be cautious about providing broad recorded statements to insurance representatives before understanding which insurer they represent and what role they play in the claim.
A rideshare accident may involve the driver's personal insurer, the TNC's carrier, another negligent driver's insurer, your own automobile insurer, health insurance companies, and potentially other entities. Statements made to one carrier can affect issues being evaluated elsewhere.
Why Are Rideshare Claims More Complicated Than Regular Car Accident Claims?
Traditional car accident cases usually begin with two questions: who caused the collision and how much insurance is available?
Rideshare cases add another layer: what was happening on the platform?
The exact moment a ride request was accepted can move a driver from one insurance period to another. The passenger entering the vehicle creates another important transition. If someone else causes the crash, UM/UIM coverage may need to be examined. Multiple applications may be involved. Personal and commercial policies may contain different terms.
The case can become even more complicated when several people are injured and multiple liability policies are involved.
For someone injured in san diego, a rideshare collision may occur during an airport pickup, downtown ride, freeway trip, late-night transportation, or ordinary neighborhood pickup. The location may change, but the insurance analysis still begins with reconstructing the driver's precise status at the moment of impact.
Why Does the 2026 California Insurance Change Matter?
Accident victims should be careful when reading older online information about California Uber and Lyft insurance.
California previously required $1 million in uninsured and underinsured motorist coverage during the passenger portion of a TNC ride. State legislation changed that requirement beginning in 2026.
Current California law requires the transportation network company to provide Period 3 UM/UIM coverage of $60,000 per person and $300,000 per incident.
The separate $1 million primary liability requirement remains important from the time the rideshare driver accepts a passenger request through completion of the ride.
The distinction matters because liability coverage and UM/UIM coverage address different situations.
If the Uber or Lyft driver causes the collision, the $1 million primary liability coverage applicable during an accepted trip can be central to the case.
If an uninsured or insufficiently insured third-party driver causes a crash while you are a rideshare passenger, the current Period 3 UM/UIM limits can become central instead.
Using outdated insurance numbers can lead an injured person to misunderstand the amount and type of coverage that may actually be available.
Why Does Medical Evidence Matter in a Rideshare Injury Claim?
Identifying a $1 million insurance policy does not mean an insurance company will voluntarily pay the full value of an injury claim.
The insurer can still examine whether the collision caused the claimed injuries, whether treatment was medically necessary, whether prior conditions contributed to symptoms, how long recovery should reasonably take, and whether future treatment is supported by medical evidence.
This is where the medical side of a personal injury case becomes particularly important.
AK Injury Law Firm founder Dr. Azadeh Keshavarz worked as a doctor of chiropractic before becoming a personal injury attorney. Through that experience, she saw how accident patients could struggle not only with physical injuries but also with insurance companies questioning their treatment and recovery.
That perspective led her to personal injury law.
A strong rideshare injury claim requires more than identifying insurance. It requires connecting the mechanics of the accident to the injuries, medical treatment, limitations, financial losses, and long-term consequences supported by the evidence.
Why Does Strategy Matter When Dealing With Uber and Lyft Insurance?
An aggressive demand without a properly developed case gives an insurance company opportunities to challenge the claim.
A strategic claim starts by identifying the correct coverage period, preserving platform information, determining who caused the collision, locating every relevant insurance policy, documenting the injuries, and anticipating the arguments the insurers are likely to make.
Sometimes the correct strategy is to pursue the rideshare driver's TNC liability policy. Sometimes another driver's insurance is primarily responsible. Sometimes UM/UIM coverage must be investigated. In other cases, several policies and defendants may need to be evaluated together.
The strongest approach is not necessarily the loudest one. It is the approach built around understanding the evidence before the insurance company has an opportunity to define the case on its own terms.
That is the thinking behind AK Injury Law Firm's philosophy: Outthink, Outfight, Outwin.
How We Can Help
AK Injury Law Firm helps people injured in Uber, Lyft, and other rideshare accidents determine what insurance actually applied when the collision happened and how the claim should be pursued. Led by Dr. Azadeh Keshavarz, a former doctor of chiropractic who became a personal injury attorney after seeing how insurance companies treated accident patients, our female-owned San Diego firm approaches these cases from both the medical and legal sides. We can investigate whether the driver was offline, waiting for a request, traveling to a pickup, or carrying a passenger; identify the applicable rideshare, personal, liability, and UM/UIM policies; preserve evidence from the platform; develop the medical evidence supporting the injuries; and challenge insurance-company arguments with a strategy built around the facts. We do not believe every fight should be fought the same way. The goal is to understand where the leverage is, prepare the case intelligently, and fight where it can make the greatest difference for the client. That is how AK Injury Law Firm approaches Outthink, Outfight, Outwin.
- California Public Utilities Commission: TNC insurance requirements
- California Insurance Code section 11580.2 (uninsured motorist coverage)
Related: San Diego Uber and Lyft accident lawyer · San Diego car accident lawyer. Need help with your own case? Request a free case review.